TL;DR: An insurance roof inspection in Oklahoma is an on-site visit by your carrier’s field adjuster to document hail, wind or storm damage tied to a specific date of loss. The adjuster walks each slope, photographs and counts impacts, measures the roof, and produces a scope of loss and a line-item estimate. You can have your own roofer there to show the adjuster the damage they documented, and a good one does that at no charge.
Who Conducts the Insurance Roof Inspection in Oklahoma?
The insurance roof inspection is conducted by a field adjuster assigned by your carrier after you open a claim. During hail season, carriers often supplement their staff adjusters with independent adjusters contracted per claim, sometimes traveling in from out of state to handle the volume. Both have the same authority to document damage and write a scope, but an adjuster working back-to-back claims can move fast and miss things. You don’t get to pick which adjuster shows up. You can have your own registered Oklahoma roofer on the roof to show them the damage.
The adjuster works for the carrier, not for you. Their job is to document the loss and write the carrier’s estimate of it, which is not always the same as a complete scope.
What Happens Step by Step During the Inspection
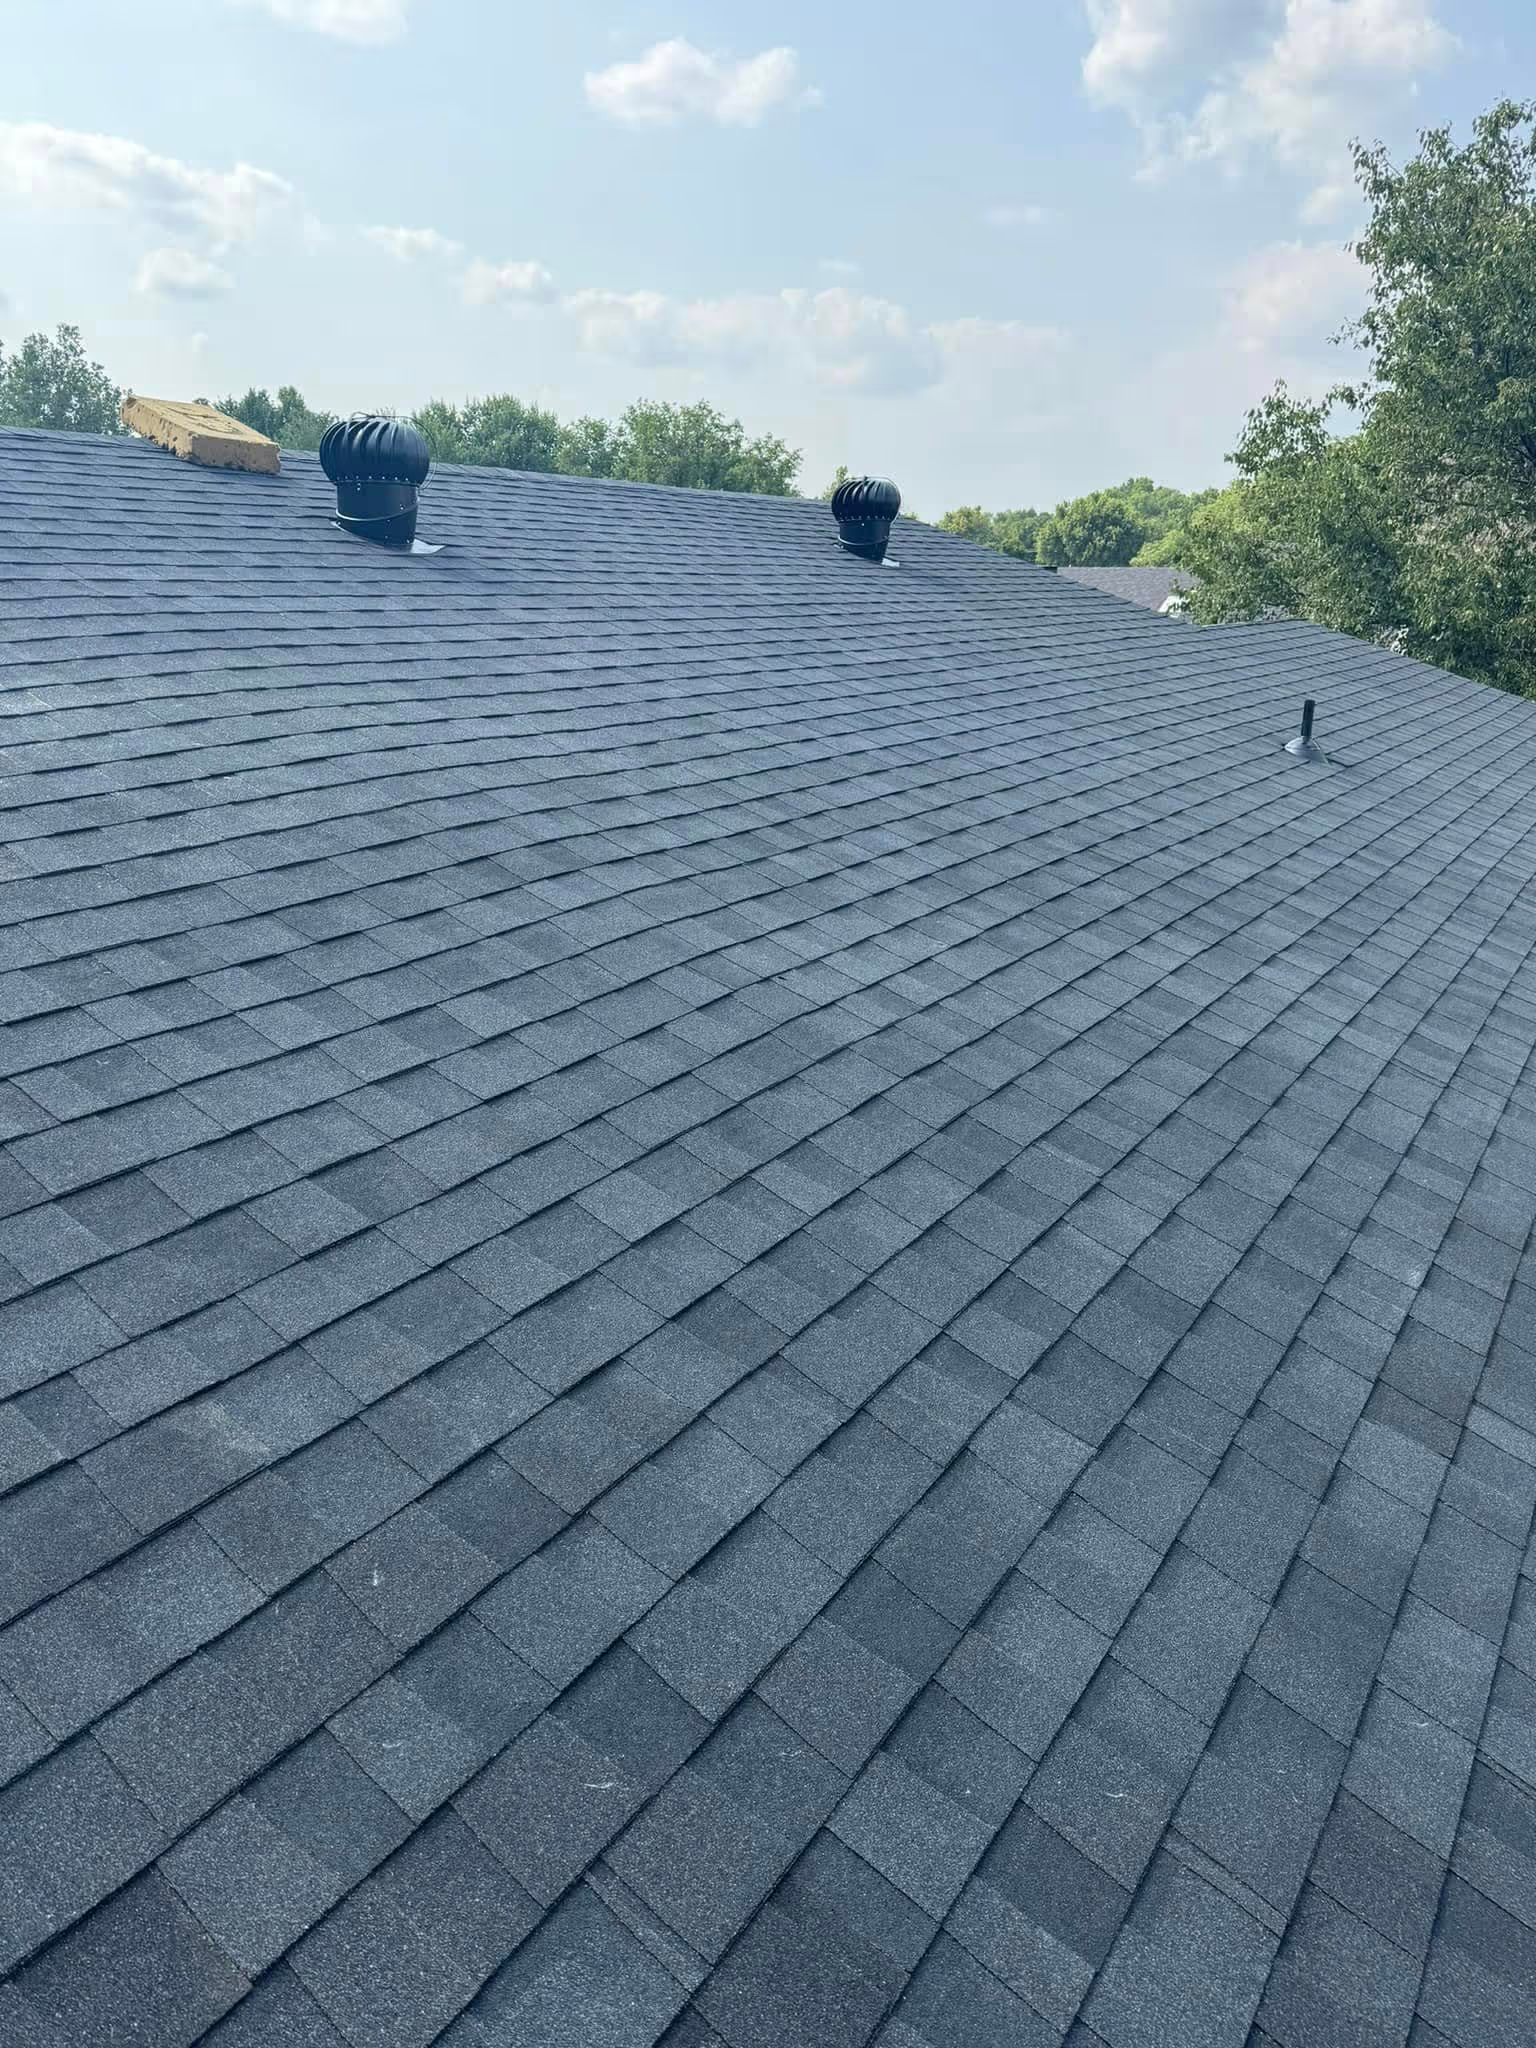
How long the inspection takes depends on the size and complexity of the roof and how much damage there is to document. The adjuster arrives with a ladder, chalk, a camera, and a measuring wheel or laser measure. They walk each slope systematically, chalk-mark hail impacts in a test square (commonly 10 feet by 10 feet per slope), count impacts per square, photograph damaged areas with a reference marker, check flashing, skylights, penetrations and ridge caps, and note underlayment and decking condition where visible.
On the ground afterward, they measure the roof, check gutters, AC fins, window screens and siding for matching impact patterns, look at the interior for water damage, and ask you about the storm date, prior claims and any recent roof work. Some adjusters give a verbal preliminary read on site. The written scope and estimate come later.
What the Adjuster Looks For, and What Gets Missed
Adjusters look for hail bruising (soft spots or fractures in the shingle mat), broken shingles, concentrated granule loss with exposed asphalt, creased or torn shingles from wind, damaged flashing, and collateral damage on gutters and other soft metals that helps confirm the hail’s size and direction. They also look for reasons a loss isn’t covered: prior repairs, wear that points to age rather than storm damage, maintenance issues, and evidence that the damage predates the date of loss. Some Oklahoma policies also exclude cosmetic damage, meaning dents or marks that don’t affect the roof’s ability to shed water.
Items that are commonly left off a first estimate: drip edge (required at eaves and rakes under the building code Oklahoma has adopted), starter strips, ridge vents and pipe boots, chimney step and counter flashing, ice-and-water membrane in valleys, and decking that can only be seen after tear-off. Whether code-required items are paid depends on whether your policy has Ordinance or Law coverage. Matching is a common question too. Oklahoma has no statute or regulation requiring insurers to replace undamaged shingles to get a match. Whether mismatched slopes are covered depends on your policy’s “like kind and quality” language. For more, see does Oklahoma require insurers to match shingles?. Missed line items are why supplements are common on legitimate hail claims.
Why You Want Your Roofer On-Site for the Inspection
A registered Oklahoma roofing contractor attending the inspection helps in four ways. First, they walk the roof with the adjuster and point out damage the adjuster might miss on a fast walk, especially on steep or complex roofs. Second, they can describe the underlayment, flashing and ventilation conditions they documented during their own inspection. Third, they can confirm that the impact count per slope gets recorded accurately. Fourth, they photograph the roof in parallel, producing a second evidence file if anything is questioned later.
Know where the line is. A roofer can inspect, document, show the adjuster the damage, and submit supplements for line items in their estimate. Under Oklahoma law, a roofer may not represent you on the claim, negotiate your settlement or advocate for coverage. That’s the role of a licensed public adjuster (36 O.S. §§6202, 6220). A contractor who wants to charge a “claim representation fee” or asks you to sign a power of attorney over your claim is a red flag. For the full claim process from the homeowner’s side, see our guide on how to file a roof insurance claim in Oklahoma City.
What Happens After the Inspection
Oklahoma law sets the insurer’s clock. The carrier must acknowledge a claim within 30 days, and within 60 days of receiving proof of loss it must accept the claim, deny it, or explain why it needs more time to investigate (36 O.S. §§1250.4, 1250.7). The carrier then issues a written scope of loss and a line-item estimate, often built in Xactimate. The scope summarizes what was approved, what was denied, and any conditions. The estimate lists the line items: shingles per square, underlayment, ice-and-water membrane, flashing, ridge cap, debris removal and labor, priced at the carrier’s area rates. Compare it line by line against your roofer’s estimate. Your roofer can submit a supplement for items their estimate covers that the carrier’s estimate missed.
The Oklahoma Insurance Department says roofs here are typically covered on an actual-cash-value (ACV) basis, meaning replacement cost minus depreciation, though your policy controls. On a replacement-cost (RCV) policy, the first check is usually the ACV amount minus your deductible, and the recoverable depreciation is released after the work is completed and the final invoice is submitted. If the claim is denied in whole or in part, Oklahoma law gives you 72 hours after the written denial to cancel a residential roofing contract (59 O.S. §1151.21). If coverage itself is in dispute, a licensed public adjuster or an attorney is the right next call, not a roofer. See our insurance claim assistance page for what we do and don’t do on a claim.
Schedule a Free Pre-Claim Roof Inspection With Prodigy Restoration
Prodigy Restoration is a BBB-accredited Owens Corning Preferred Contractor serving the OKC metro. We offer free roof inspections with photo documentation, meet your adjuster on the roof to show the damage, and submit supplements for line items our estimate covers. Call us at (405) 730-5672 or contact us.
Frequently asked questions
How long does an insurance roof inspection take in Oklahoma?
It depends on the size and complexity of the roof and how much damage the adjuster needs to document. Large or complex roofs take longer. The written scope of loss and estimate come later. Oklahoma law requires the insurer to accept, deny or explain the need for more investigation within 60 days of receiving proof of loss.
Do I have to be home during the insurance roof inspection?
It's a good idea. The adjuster may want to see the attic and any interior water damage, and may ask you about the storm date and prior roof work. Your roofer can be there for the exterior roof walk to show the adjuster the damage they documented. Plan to be available for the whole visit.
Can I get a free roof inspection from a local Oklahoma contractor before my insurance adjuster comes out?
Yes, and it's worth doing. An inspection from a registered local roofer before the adjuster arrives gives you photo documentation of the damage and a line-item estimate to compare against the carrier's scope. It can also tell you whether the damage is likely to exceed your deductible before you file. Prodigy Restoration offers free roof inspections.
What if the insurance adjuster denies my roof claim?
Read the denial letter and the policy language it cites. If the dispute is about missed damage, your roofer can document it with photos and your carrier can reinspect. If the dispute is about coverage itself, a licensed public adjuster or an attorney can represent you; a roofer cannot. You can also file a complaint with the Oklahoma Insurance Department. After a written denial, you have 72 hours to cancel a residential roofing contract.
Will the adjuster actually walk my roof?
Usually, on a walkable residential roof in normal conditions. On very steep or tall roofs, or when weather makes a walk unsafe, an adjuster may use a drone instead. On a walkable roof, you can ask for an on-roof inspection, because hail bruising in the shingle mat is confirmed by touch, which photos alone can miss.
Prodigy Restoration
7140 NW 112th St, Oklahoma City, OK 73162