TL;DR: When an insurance adjuster grades hail damage in Oklahoma, the question isn’t whether hail hit the roof. It’s whether the hits are functional damage (a fractured mat, a puncture, exposed asphalt) and how many of them land in the test square on each slope. In Oklahoma City, the carrier’s own guideline, not a state rule, decides whether that count means repair or replacement.
How an insurance adjuster grades hail damage in Oklahoma decides most of what happens to a roof claim. Two homeowners on the same street can get very different results from the same storm, because the grade depends on the type of damage, where it sits and how many hits the adjuster counts on each slope. Knowing how that grading works helps you read your estimate and ask better questions. It also shows why the documentation from your own inspection matters. If you’re still at the start of the process, our roof insurance claim help page explains what we do on a claim and what the homeowner handles.
How Do Insurance Adjusters Grade Hail Damage?
Adjusters grade hail damage by sorting every mark on the roof into one of two groups: functional or cosmetic. Functional damage reduces the roof’s ability to shed water. Cosmetic damage changes how the roof looks but not how it works. Only the first group counts toward a repair or replacement on most policies.
What counts as a hit
On asphalt shingles, the test adjusters use is hail bruising and mat fracture. A countable hit is usually a circular impact mark with exposed asphalt, a soft spot that gives under thumb pressure, or a fracture in the fiberglass mat under the granules. A puncture, a cracked shingle or broken flashing also counts. These are the marks the adjuster circles in chalk and photographs.
What doesn’t count
Granule loss alone can be cosmetic or normal aging, so a thin patch of granules with no bruise under it often won’t be counted. Blisters don’t prove hail either, since they are often age-related. On wind claims, a lifted tab that is still intact isn’t damage by itself. A horizontal crease, a tear or a missing tab is. Good inspection photos show which marks meet that standard and which don’t.
Test Squares and Hit Counts, Slope by Slope
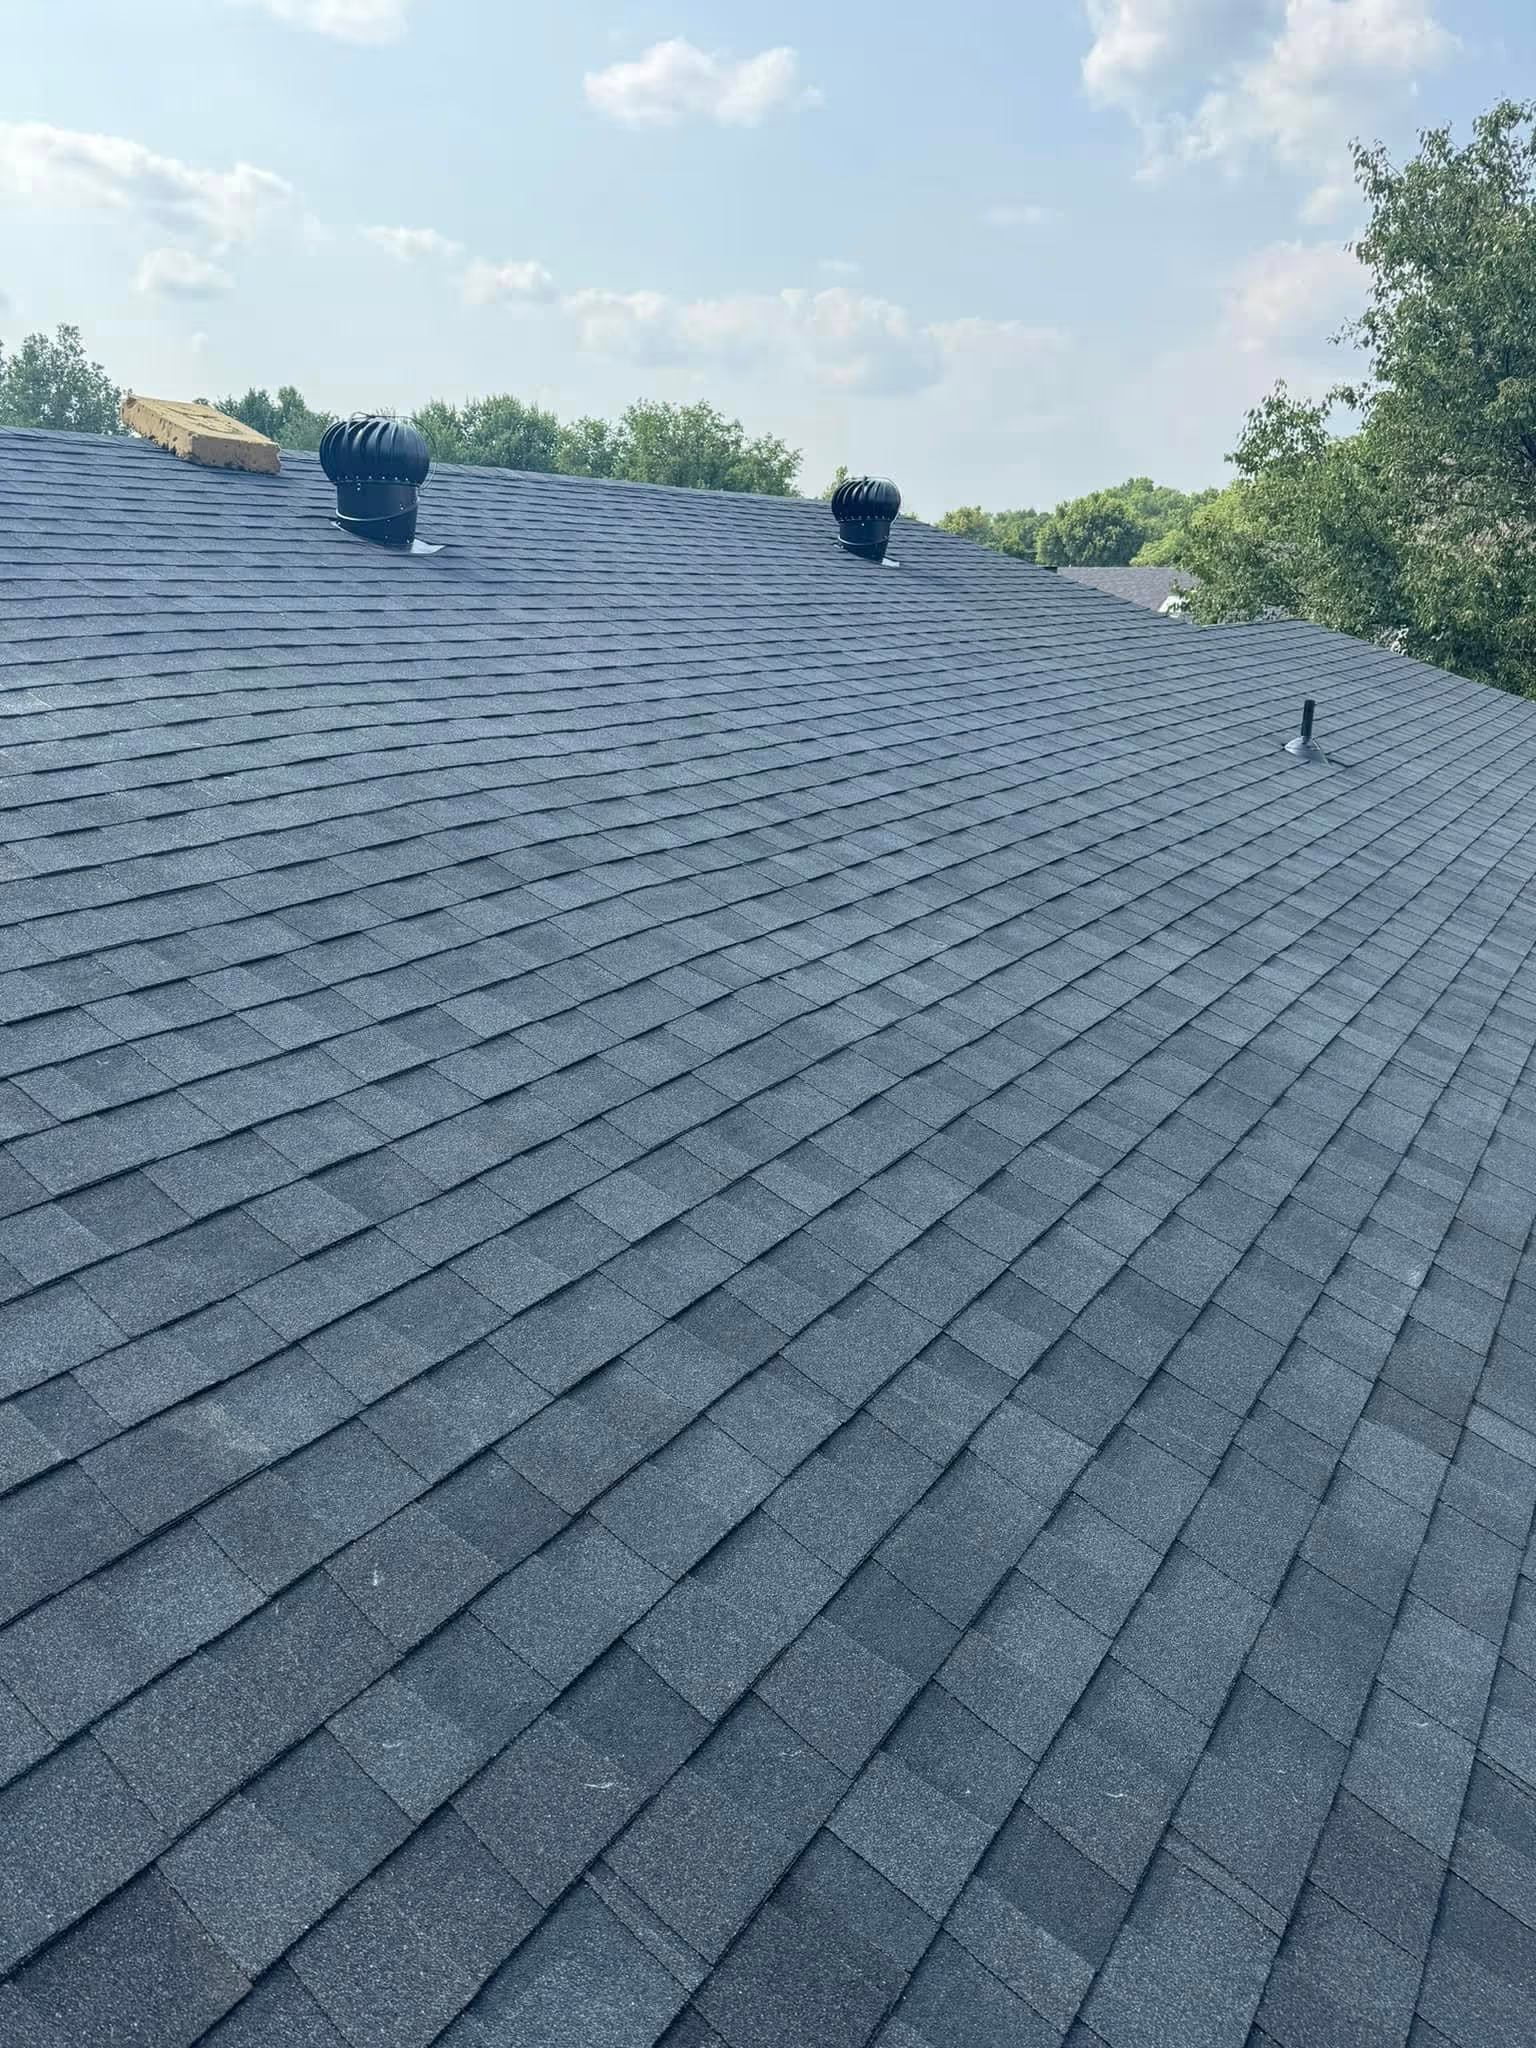
The adjuster hail test square is the heart of the grade. On each slope, the adjuster marks off a test square, chalks every hit inside it that meets the functional standard, and records the count. Slopes are graded separately. A storm-facing slope can qualify while the slope on the other side of the ridge doesn’t.
How many hits are enough is set by the carrier. Adjusters and roofers sometimes call these hail damage brackets or thresholds: a count below the carrier’s line points to repair, and a count above it points to replacing the slope. No Oklahoma statute or rule sets that number, and it can differ from one insurer to the next. That’s why a hit count on its own tells you little until you know how your carrier reads it.
Collateral damage sets the scene
Before the adjuster climbs, the soft metals on the house help confirm the storm. Dents on gutters, downspouts, vents and AC fins show the hail’s direction and rough severity. Dent size is not a one-to-one measure of stone size, though, and soft-metal dents don’t prove shingle damage by themselves. The adjuster also ties the claim to a date of loss, which can be checked against National Weather Service Storm Data. For what those marks look like from the ground, see our guide on how to spot hail damage.
How the Grade Becomes Your Estimate
Once the slopes are graded, the adjuster turns the counts into a scope of loss. Isolated hits on one slope usually become a repair line. Functional damage spread across several slopes usually points toward replacement. The written estimate then lists line items such as shingles, underlayment, flashing, ridge cap and debris removal.
A few Oklahoma specifics shape what that estimate pays:
- Actual cash value is typical. The Oklahoma Insurance Department (OID) says roofs here are usually covered on an actual-cash-value basis, meaning replacement cost minus depreciation. Your policy controls.
- Cosmetic exclusions exist. OID warns that some policies exclude damage that affects appearance but not function, which makes the functional grade even more important.
- Matching isn’t required by law. Oklahoma has no statute or rule requiring insurers to replace undamaged slopes for a match. It depends on your policy’s like-kind-and-quality language. Our post on whether Oklahoma requires insurers to match shingles covers this in detail.
- Code items depend on coverage. Items like drip edge, which the building code requires at eaves and rakes, are paid only where the policy has Ordinance or Law coverage.
- Deductibles are often a percentage. OID says separate wind and hail deductibles are typically 1% or 2% of insured value.
What This Means for Oklahoma City Homeowners
Roofs across the OKC metro take several small hail events in a typical year, and that history shows up in the grade. Research on weathered shingles found that repeated sub-severe hail leaves them much more vulnerable to the next severe storm. An adjuster still has to separate old wear from new impacts, so dated photos from before and after a storm help a great deal.
The metro’s documented storms are the reference points adjusters use. On 2024-09-24, the National Weather Service recorded 2.50” hail about 4 miles west-southwest of Edmond, with 1.75” to 2.33” common across Oklahoma City and Norman. When a claim lines up with an event like that, the date of loss is easy to support.
Timing matters too. Oklahoma requires an insurer to acknowledge a claim within 30 days and, within 60 days of proof of loss, to accept it, deny it or explain why it needs more time (36 O.S. §§1250.4, 1250.7). A policy can also shorten the time to sue to no less than one year from the loss (36 O.S. §3617), so check your policy’s deadline rather than assuming one.
Where Your Roofer Fits in the Grade
The grade belongs to the carrier, and the claim belongs to you. The homeowner files it and makes the decisions on it. A roofer’s role is narrower, and Oklahoma law draws the line clearly.
On a claim, we inspect the roof, document the damage with photos, and meet the adjuster on the roof to show the hits we found on each slope. After the estimate comes back, we submit supplements for line items in our estimate that the carrier’s scope missed. For a walkthrough of that visit, see what to expect at the adjuster’s inspection.
What a roofer can’t do is negotiate your settlement, represent you or advocate for coverage. Under 36 O.S. §§6202 and 6220, that work is reserved for licensed public adjusters. If you disagree with how a slope was graded because damage was missed, photos and a reinspection request are the usual first step. If the dispute is about coverage itself, such as a cosmetic exclusion or a denial, a licensed public adjuster or an attorney is the right call. Oklahoma caps a public adjuster’s fee on a declared-catastrophe residential claim at 10% of the settlement (36 O.S. §6218). Also walk away from any contractor who offers to pay or rebate your deductible, which is illegal under 59 O.S. §1151.30.
Get Your Roof Inspected Before the Adjuster Grades It
Knowing how an insurance adjuster grades hail damage in Oklahoma is easier when you already have your own photos of every slope. Prodigy Restoration offers free roof inspections across Oklahoma City and the metro, and we’re BBB Accredited and an Owens Corning Preferred Contractor. We answer calls 24/7. Call us at (405) 730-5672 or fill out our contact form.
Frequently asked questions
How do insurance adjusters measure hail damage on a roof?
Adjusters mark a test square on each slope and count the hits inside it that are functional damage: bruises with a fractured mat, soft spots, exposed asphalt or punctures. Granule loss alone and blisters usually don't count. They also check gutters, vents and other soft metals to confirm the storm's direction, and tie the claim to a date of loss.
How much hail damage does it take to replace a roof?
There is no Oklahoma rule that sets a number. Each carrier uses its own guideline for how many functional hits in a test square justify replacing a slope rather than repairing it. Damage spread across several slopes usually points toward replacement, while isolated hits on one slope usually become a repair. Your policy and carrier decide the outcome.
Does cosmetic hail damage count on an Oklahoma roof claim?
Often it doesn't. The Oklahoma Insurance Department warns that some policies exclude damage that changes how a roof looks but not how it sheds water. Dents or color changes with no loss of function may fall under that exclusion. Read your policy or renewal for cosmetic damage language before you file, and ask your agent what it covers.
How do I work with my insurance adjuster on a roof claim?
Have your own roof inspected first so you have dated photos of every slope. Be available on inspection day, share the storm date, and have your roofer on the roof to show the damage they documented. Compare the carrier's estimate line by line with your roofer's. If coverage itself is disputed, a licensed public adjuster or an attorney can help.
Can my roofer argue with the adjuster about the hit count?
No. A roofer can show the adjuster the damage, share photos and submit supplements for missed line items, but Oklahoma law does not allow a roofer to negotiate your settlement or advocate for coverage. That role belongs to a licensed public adjuster. If damage was missed, asking the carrier for a reinspection with your photos is the usual first step.
Prodigy Restoration
7140 NW 112th St, Oklahoma City, OK 73162