TL;DR: In Oklahoma, you should file a hail claim for small damage only when a registered local roofer has documented real storm damage in writing, the repair cost clearly exceeds your deductible, and the damage is tied to a dated storm event. Filing on cosmetic granule loss or damage that does not exceed your deductible can create a CLUE report entry without producing a payout, which can hurt you at renewal without solving anything.
The Short Answer: Should You File?
File a small hail claim in Oklahoma only when three conditions are true at the same time. First, a CIB-registered OKC roofer has inspected the roof and produced a written damage report that ties impacts to a specific dated storm. Second, the contractor’s estimate clearly exceeds your wind/hail deductible: not “might” or “close to,” but exceeds it by enough to produce a real payout. Third, no carrier-specific roof age endorsement, cosmetic exclusion, or recent claim history makes the filing risky to renewal.
If all three are true, filing is the right call. If any one of them is missing, you often come out ahead by paying for a small repair out of pocket and preserving a clean CLUE report for renewal.
What Counts as “Small” Hail Damage in Oklahoma?
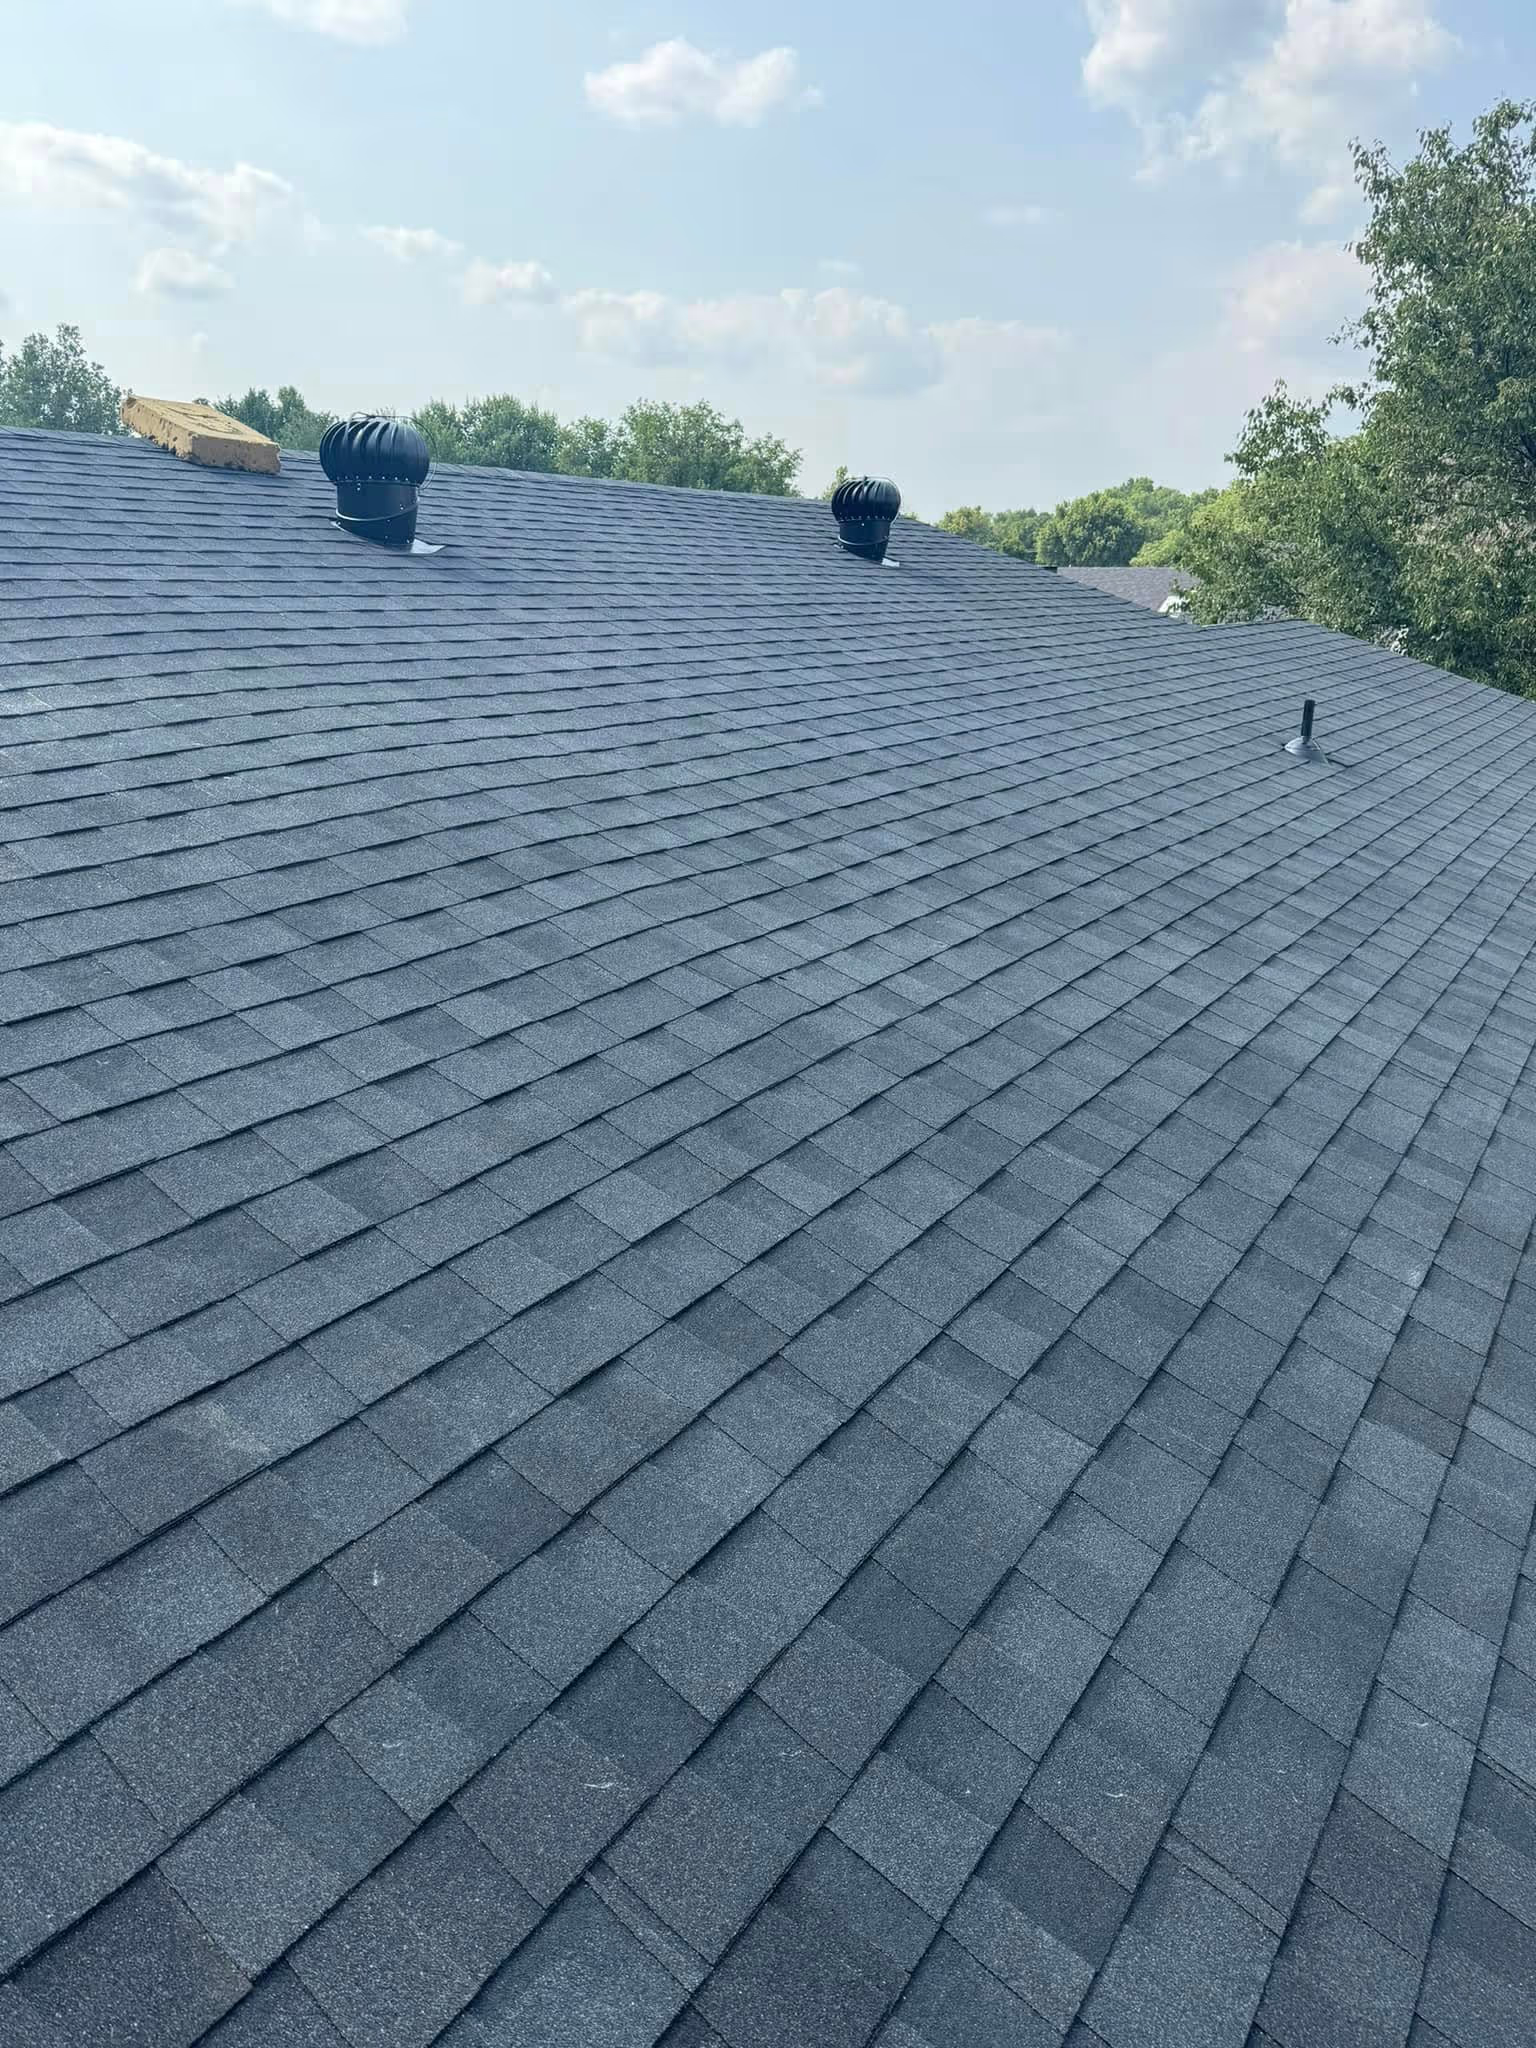
“Small” hail damage in the OKC metro generally means one of three patterns. First, localized damage on a single slope, with a limited number of impacts that a good installer can repair without a full replacement. Second, granule loss without shingle bruising, which looks alarming but can be cosmetic or normal aging rather than storm damage. Third, damage from a marginal hail event where the stones in your area were small. Smaller hail is less likely to fracture a shingle’s mat, though research shows repeated small hail can wear down older, weathered shingles more than you’d expect, so “small hail” doesn’t always mean “no damage.”
Moderate-to-severe hail damage (multiple bruised slopes, fractured mat, exposed fiberglass, or bent metal accessories) is a full-replacement conversation, not a “small claim” question. If that is what you are looking at, skip this article and go straight to our walkthrough on how to file a roof insurance claim.
The Cost-Benefit Math of a Small Hail Claim
The math on a small claim comes down to four numbers. The first is your wind/hail deductible, which in Oklahoma is often 1% to 2% of dwelling coverage. On a typical metro home, that percentage deductible can swallow a “small” repair entirely before any payout is released. The second is the legitimate repair cost from a registered roofer’s estimate. The third is the payout math: on an RCV policy, the carrier pays the repair cost minus your deductible; on an ACV policy, which the Oklahoma Insurance Department says is typical for roofs here, depreciation further reduces the check. The fourth is the premium and renewal impact, which is harder to price but real.
If the repair cost is under or close to your deductible, there is no payout and the claim produces no upside: only a possible CLUE report entry. If the repair cost is well above the deductible, the claim math usually justifies filing. Anywhere in between, the smart move is often to pay for the repair out of pocket and preserve a clean claim history.
When Filing a Small Hail Claim Is Worth It
A small claim is worth filing when the repair estimate clearly exceeds your deductible and the damage is documented against a major, widely recorded hail event. It is also worth filing when multiple items are damaged alongside the roof (dented gutters, AC fin damage, window screen destruction) because the combined claim scope can cross the deductible threshold even when the roof alone would not. And it can be worth filing when the damage is real but your roof is near the end of its useful life, since covered storm damage may lead to a replacement, though on an ACV policy, depreciation on an older roof can shrink the payout significantly.
The quiet win case is the roof that looks fine from the ground but shows clear impact bruising on the inspection report. Bruising and mat fractures are the functional damage adjusters look for, so if a registered contractor documents them in writing with photos, the claim deserves a serious look.
When You Should Skip the Claim
Skip the claim when the repair cost is under or near your deductible: the math does not work in your favor. Skip when the damage is pure cosmetic granule loss that your contractor cannot tie to a specific storm, because carriers deny these and the claim can still leave a CLUE mark. Skip when your policy has a cosmetic damage exclusion or a roof age endorsement that caps payout on older roofs. Think hard before filing if you’ve already filed several claims in the last few years, since claim frequency can affect renewal. In any of these cases, a legitimate local roofer can usually handle a spot repair, and the cost will depend on how many shingles, how much flashing, and which slopes are involved. That is when a straightforward roof repair, paid out of pocket, is the right path.
Get a Free Hail Damage Inspection From a BBB-Accredited Oklahoma Roofer
Prodigy Restoration is a BBB-accredited, Owens Corning Preferred roofing contractor serving the OKC metro. We inspect your roof at no cost, document what’s storm damage and what isn’t, and tell you honestly whether the numbers favor a claim, before you ever call your carrier. The decision is yours. We answer calls 24/7 at (405) 730-5672, or you can fill out our contact form.
Frequently asked questions
Is it worth filing a hail claim if the damage is under my deductible?
Usually not. If the documented repair cost is under your wind/hail deductible, the claim cannot produce a payout, and the filing can still create a CLUE report entry that carriers see at renewal and when you shop for a new policy. Claims can stay on a CLUE report for up to seven years. Paying for the repair out of pocket is usually the better move.
Will filing a small hail claim raise my homeowners insurance in Oklahoma?
It depends on your carrier and your claim history. Every claim, approved, denied, or withdrawn, can be recorded on your CLUE report, and a pattern of claims in a short window can affect renewal eligibility as well as price. Ask your agent how your carrier treats weather claims before you file a marginal one.
How do I know if my "small" hail damage is actually codable damage?
Only a professional roof inspection can tell you for sure. Impact bruising (a soft spot where the hail strike fractured the shingle's mat) and exposed asphalt are the functional damage adjusters look for. Granule loss alone is often cosmetic or normal aging. A CIB-registered Oklahoma roofer will photograph each slope and produce a damage report showing what they found.
Can I get a small hail repair done without filing an insurance claim?
Yes, and for many Oklahoma homeowners it is the better financial decision. A reputable local contractor can spot-repair a handful of damaged shingles, replace dented flashing, or re-secure lifted tabs. The cost depends on how much needs fixing, where it is on the roof, and how easy the roof is to reach. The repair should still be documented with photos in case the next storm produces a larger claim and the prior damage needs to be separated from the new event.
Does an approved small hail claim put my house on an insurance watch list?
Not a formal "watch list," but claims, approved or denied, can be logged on your CLUE report, which carriers check at renewal and when you shop a new policy. Several claims in a short window can make renewal harder. Treat every claim like it counts, even a small one.
Prodigy Restoration
7140 NW 112th St, Oklahoma City, OK 73162